


- Blog Post
- Step Inside Accounting, Self-Employee
IRS payments on account: 5 rules so you are not caught by surprise
Step Inside Accounting · Practical guide
#StepInsideAccounting
1. Understand what they are and who pays them
Payments on account (pagamentos por conta) are advance payments of the IRS for the current year. Instead of paying all the tax at once at the annual settlement, you pay part of it during the year, in three instalments. They are not an extra tax: everything you pay is deducted when you file your IRS return.
They are paid by self-employed workers and sole traders, under the simplified regime or with organised accounting. But there are only payments on account when, two years earlier, you had income as a self-employed worker and the IRS for that year was not fully covered by withholding tax. So:
- in the year you open your activity and the following year, as a rule, there are no payments on account;
- if your clients withhold IRS on every invoice, the amount may be low or there may be none at all;
- if you work mainly with foreign clients, private individuals or with the withholding waiver, you will very probably have to pay.
2. Know how the amount is calculated
The calculation uses the data from your IRS of two years earlier: the payments on account for 2027, for example, are calculated from your 2025 IRS. This is how it works:
- it starts from the IRS assessed for that year, after deductions (general family expenses, health, education, dependants), but before withholding is taken off;
- only the part corresponding to your self-employed income is kept – if you also had a salary, for example, only the proportion of self-employed income counts;
- the withholding your clients made that year is deducted;
- 65% is applied to the result.
The final amount is split into three equal instalments, rounded up to the next euro. If an instalment is below €50, you do not have to pay it.
3. Mark the deadlines: July, September and December
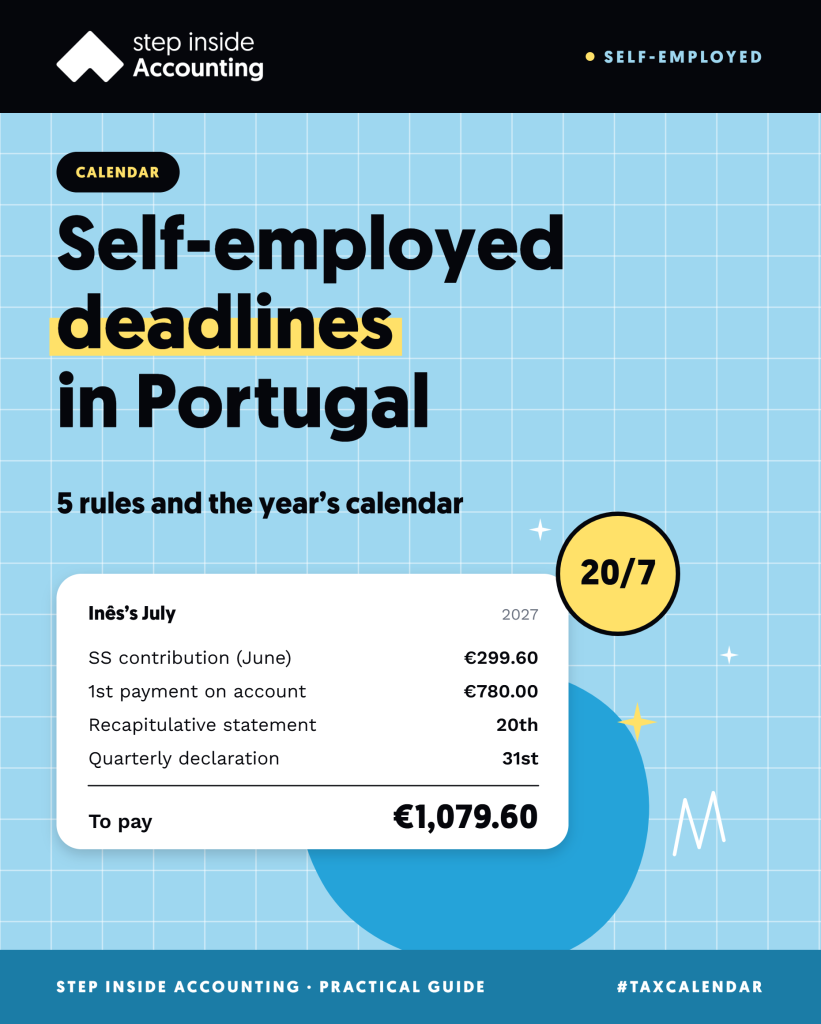
The three payments are due by 20 July, 20 September and 20 December. When the 20th falls on a weekend or public holiday, the deadline moves to the next working day – in 2026, the last payment is due by 21 December, because the 20th is a Sunday.
The amount appears in the IRS assessment notice from two years earlier, and the Tax Authority sends the payment slip in the month before each deadline. You can also find it on the Portal das Finanças, under Pagamentos, in Pagamentos a decorrer: that is where the references are to pay by Multibanco, home banking or MB WAY. If you miss a deadline, interest and a fine may apply, so put the three dates in your calendar.
4. If your income has dropped, you can reduce or stop paying
As the calculation looks at the past, it may not match your current year – for example, if you invoiced a lot two years ago and lost clients this year. In those cases, you can:
- stop paying, if the withholding already made this year, plus the payments on account you have already made, is enough to cover the IRS you expect to pay for the year;
- reduce an instalment, when it is higher than the difference between the IRS you expect and what you have already paid;
- stop paying, if you have closed your activity and no longer have self-employed income.
The decision is yours, but it carries a risk. If the IRS settlement shows that, because of the reduction, more than 20% of what you should have paid was left unpaid, compensatory interest is charged. Do the estimate with real figures before you decide.
5. What you paid is deducted at the IRS settlement
In the annual IRS return, payments on account are added to withholding tax and deducted from the tax for the year:
- if you paid more than the final tax, you get the difference back as a refund;
- if you paid less, you pay what is missing.
Payments on account do not increase your IRS: they only change when you pay it. What weighs is cash flow – three payments in the second half of the year, at a time when you may also have VAT and Social Security to pay.
Example
Joana is a designer, is under the simplified regime and works mainly for foreign clients, who do not withhold. In 2025, her only income was as a self-employed worker:
- IRS assessed for 2025, after deductions: €4,200
- withholding by Portuguese clients in 2025: €600
- calculation base: €4,200 − €600 = €3,600
- payments on account for 2027 (65% of €3,600): €2,340
- each instalment: €780, by 20 July, 20 September and 20 December 2027
In 2027, Joana loses two clients and expects her IRS for the year to be €1,500, with no withholding. After paying the July and September instalments (€1,560), she has already covered the expected tax, so she can skip the December one. At the 2027 IRS settlement, filed in 2028, she gets a €60 refund (€1,560 − €1,500).
- If, in 2025, Joana had also had a salary and her self-employed income had been 40% of her total income, only 40% of the IRS would count. With IRS of €6,000, the base would be €1,800 (40% of €6,000 = €2,400, minus €600 of withholding) and the payments on account €1,170 (65%): three instalments of €390.
Team tip
When the first payment slip arrives, in June, review the amount with us against what you are invoicing this year. If your income has dropped, we do the estimate and tell you whether you can reduce or skip an instalment without risking interest. If it has gone up, the payments on account will not be enough: set aside part of what you receive every month for the settlement.
Want us to handle this for you?
Companies
Monthly accounting
Bookkeeping, tax obligations and managing partners’ salaries, all in one place.
€250 + VAT / month
Self-employed
Recibos verdes without the stress
Tax returns, VAT and Social Security handled by people who know the regime inside out.
from €80 + VAT / month
This article is for information only and does not replace professional advice. Figures and rules are those in force at the date of publication and may change.
Explore more resources
Share with someone who needs it
Want to know more? Explore the other Step Inside Accounting resources
- Blog Post
- Step Inside Accounting, Company
- Blog Post
- Step Inside Accounting, Self-Employee
- Blog Post
- Step Inside Accounting, Self-Employee